Michele Fulcher Apply Now

First-time buyers · Northern Michigan

The whole process, in the order it will actually happen.

Nobody is born knowing what an escrow account is, or why an underwriter wants two months of bank statements. Michele will walk you through it in sequence, tell you which documents are needed and why, and run real numbers on real listings before you write an offer.

Mortgage Loan Originator · Priority Home Mortgage · NMLS #139088

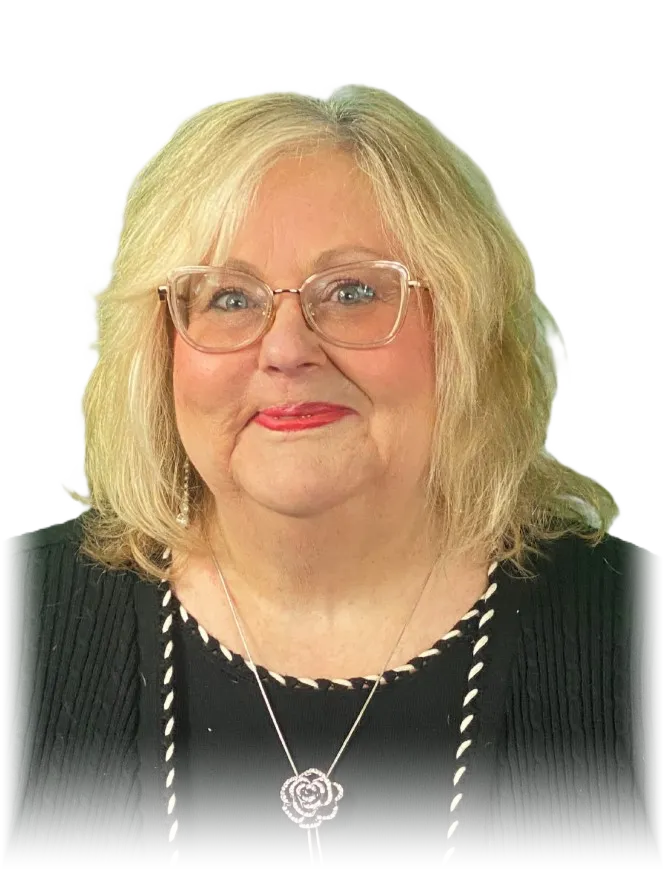
Michele Fulcher, Mortgage Loan Originator

Michele Fulcher · NMLS #139088

40 years in lending Career mortgage banker
NMLS #139088 Verified on NMLS Consumer Access
Thousands of loans closed Who’s Who nominee, two years running
Former company owner President, A.S. Financial Corporation

Before anything else

What a first house costs around here.

The median sale price in Grand Traverse County was $420,000 in the first half of 2026. One county out, in Kalkaska, Wexford, or Roscommon, the range runs closer to $225,000 to $260,000. That gap is worth understanding before you settle on a pre-approval number, because a 20 to 40 minute drive changes what your budget reaches.

Closing costs commonly run 2 to 4 percent of the purchase price on top of your down payment. On a $300,000 house that is roughly $6,000 to $12,000, and it is the number that surprises people. There are ways to reduce it, and that is part of structuring the financing.

Market figures as of August 2026. See the full snapshot on the homeowners page.

Your options

The programs, and what each one asks of you.

There is no single best loan. There is the one whose guidelines your file already meets, at the price that fits what you are trying to do. Michele will lay them side by side rather than steering you to one.

First-time buyers in Grand Traverse, Kalkaska, Missaukee, Wexford, and Roscommon counties

Your First Purchase, Explained in Order

First-time buyers need more time spent on the process, not less. We go through it in the order it will actually happen, so nothing in the file surprises you at week six.

  • FHA, VA, USDA, Fannie Mae, and Freddie Mac compared on what each one asks of you
  • Down-payment-assistance programs matched to what you qualify for, not listed at you
  • Credits that depend on where the house is rather than on your income, worth checking on any address you are serious about
  • A payment and cash-to-close estimate on real MLS listings before you write an offer
  • An insurance agent referral early, because a quote you get in week one is a number you can plan around

Buyers who are close but not yet qualified

Getting the Score You Need

A score is not a verdict. A credit simulator shows which specific action moves your number, and by how much, so you spend your effort on the one that changes your pricing.

  • Simulators run against a target score, not general advice
  • Rescoring where a correction or a paydown will actually land
  • A realistic timeline, including the cases where waiting is the cheaper move

Score changes are not guaranteed. A simulator projects; the bureaus decide.

Buyers of condos, new construction, and unusual property

Properties That Do Not Fit the Box

Northern Michigan has a lot of property that a standard checklist rejects. Most of it is financeable. The work is knowing which guideline applies and getting the answer before you are under contract.

  • Condos: conventional Fannie Mae and Freddie Mac review, FHA spot approval for unapproved projects, and non-warrantable options
  • New construction and one-time-close timing
  • Unique construction and mixed-use, including buildings with attached commercial space

Condo and non-warrantable eligibility is project-specific. Ask early, because the answer can change which building you offer on.

Plain English

The words you are about to hear a lot.

None of this is complicated once someone says it in normal language. If a term comes up that is not here, ask. There is no such thing as a question that is too basic.

Pre-approval
A lender has looked at your income, credit, and assets and put in writing what they will lend. It is what makes an offer credible. It is not a final loan approval.
Cash to close
Every dollar you need on closing day: down payment plus closing costs, minus anything the seller agreed to cover and minus your earnest money. This is the number that actually matters when you set a budget.
Closing costs
Lender fees, title work, appraisal, taxes, and the first year of insurance. Commonly runs 2 to 4 percent of the purchase price. On a $300,000 house that is roughly $6,000 to $12,000.
Escrow
A holding account. Part of your monthly payment goes into it, and the servicer pays your property taxes and homeowners insurance out of it when they come due.
PMI
Private mortgage insurance. Usually required on a conventional loan when you put down less than 20 percent. It protects the lender, not you, and it can often be removed later once you have enough equity.
DTI
Debt-to-income ratio. Your monthly debt payments divided by your gross monthly income. Underwriting uses it to decide how much house your income supports.

How it goes

What actually happens, step by step.

The same three steps she runs for every borrower. For a first purchase the second one matters most: knowing which documents are coming, and why, is the difference between a calm process and a stressful one.

  1. Match the Program to Your File

    Before any numbers go out, we look at what you have: income, credit, the down payment you can reach, and the property you are actually trying to buy. Then we find the program whose guidelines your file already meets, rather than the one with the best headline rate.

  2. Build the File Before Underwriting Sees It

    I read the underwriting guidelines and the matrix for your program, so I can tell you which documents are needed and why each one is being asked for. Requesting them up front is what keeps a file from stalling in week five over something we could have handled in week one.

  3. Work the Transaction Through Closing

    I will speak to the listing agent on your behalf to help your offer get accepted, and I am available after hours and on weekends because that is when offers are written. You hear from me in whatever way works for you and for everyone else in the transaction.

Before you talk to anyone

How much house does this actually come to?

Put in an income, a down payment, and what you pay toward debts each month, and see the price range that produces. It runs in your browser, nothing is sent anywhere, and there is no email to leave. It is the same arithmetic a lender runs first.

In their words

How clients describe working with Michele.

“She walked us through every single step in a very easy and clear way... she worked with us patiently until we completed the whole process and never felt rushed or pressed. She listened to us and helped us to create a plan that fit our needs to obtain the house that we loved!”
Rocely S. · Home purchase, reviewed 2021

From Google reviews

“Michele Sims was exceptional since day 1! She walked us through every single step in a very easy and clear way... she worked with us patiently until we completed the whole process and never felt rushed or pressed. She listened to us and helped us to create a plan that fit our needs to obtain the house that we loved! Thanks Michele!”
Rocely S. · February 2021

See all reviews on Google

Free download

The Northern Michigan Homebuyer Guide.

Fourteen pages on buying a first home up here. What you actually need for a down payment, the MSHDA money most people in these counties do not know they qualify for, why the tax bill on the listing is not the one you will pay, and which counties require a well and septic inspection before a sale can close.

One email. No drip-marketing avalanche. We won’t share your address.

No pressure, no pitch

Ask the question you think is too basic.

There isn’t one. Michele has explained this process to thousands of buyers, and the questions people apologize for asking are usually the ones that matter most.

Step 1 of 2 · What’s the situation?

Or start it yourself

You can begin the application without talking to anyone first.

Some people would rather fill something out than get on a call. The application goes straight to Michele. She reads it and calls you.

Starting it does not commit you to a loan, a lender, or a house, and it does not cost anything. If a question comes up while you are filling it out, call her and she will walk you through that part.

Opens the secure Priority Home Mortgage application in a new tab. Michele Fulcher, NMLS #139088. Equal Housing Lender.

Bought a house before? The move-up and refinance side is at buyupnorth.com/homeowners. Buying to rent out? That is buyupnorth.com/investors.