Michele Fulcher Talk it through

Priority Home Mortgage · Northern Michigan

You have bought a house before. This one is a different problem.

The second or third purchase is rarely about qualifying. It is about sequencing a purchase against a sale, deciding whether the current house becomes a rental, and writing an offer a listing agent will take seriously. Michele Fulcher has spent 40 years on those decisions, across every rate environment since the mid-1980s.

Mortgage Loan Originator · Priority Home Mortgage · NMLS #139088

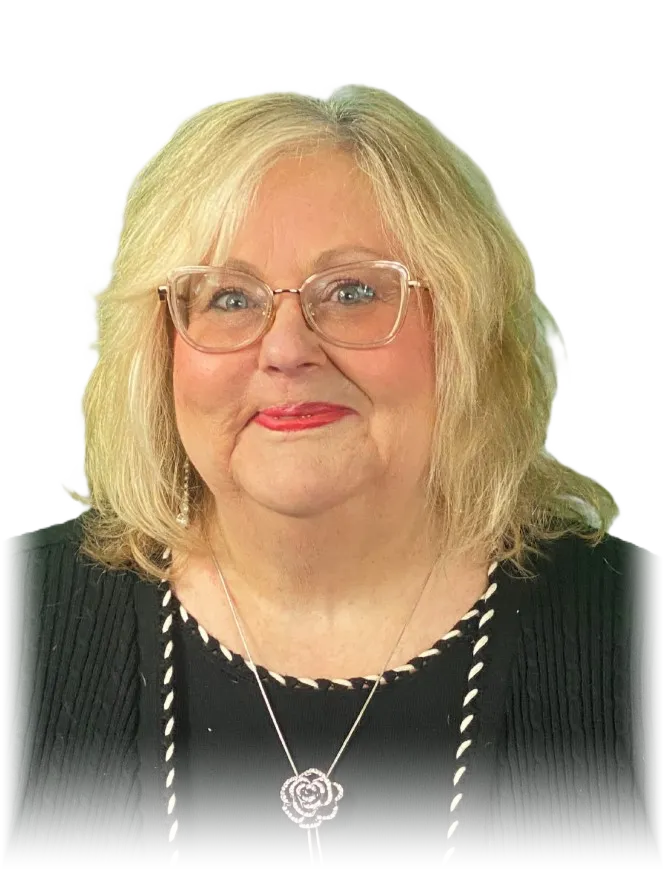
Michele Fulcher, Mortgage Loan Originator

Michele Fulcher · NMLS #139088

40 years in lending Career mortgage banker
NMLS #139088 Verified on NMLS Consumer Access
Thousands of loans closed Who’s Who nominee, two years running
Former company owner President, A.S. Financial Corporation

Where the money actually is

Structure, not just approval.

Most of what determines whether a move works is decided before underwriting ever opens the file. Which program your file already fits. What the equity in your current house frees up after the costs of selling. Whether discount points pay for themselves before you are likely to move again. Whether the condo you like is going to clear project review.

Those are the conversations worth having first.

What she works on

The situations that come up on a second or third purchase.

None of these are unusual. They are the parts of a move that a rate quote does not answer, and the parts where getting the order right saves real money.

Homeowners who need the next house before the current one closes

Buying Before You Sell

The problem is rarely qualifying. It is sequencing. We work out what you can carry between the two closings, and what the offer has to say for a seller to take it.

  • What your equity actually frees up, after the costs of selling
  • Whether the current home is a sale or a rental, with the numbers for both
  • Offer terms that survive a contingency: concessions, timing, and what a listing agent will read as strong

Bridge and buy-before-you-sell options vary by program and by your equity position. We confirm what is available before we plan around it.

Homeowners weighing a refinance or a cash-out

Rate, Points, and the Break-Even

Buying down a rate is arithmetic, not a favor. You should see the break-even month before you decide, and you should know what happens if you move or refinance before you reach it.

  • Discount points priced out against the month they pay for themselves
  • Cash-out versus a second lien, compared on total cost rather than on rate alone
  • What removing mortgage insurance is worth, and what it takes to get there

Buyers of condos, new construction, and unusual property

Properties That Do Not Fit the Box

Northern Michigan has a lot of property that a standard checklist rejects. Most of it is financeable. The work is knowing which guideline applies and getting the answer before you are under contract.

  • Condos: conventional Fannie Mae and Freddie Mac review, FHA spot approval for unapproved projects, and non-warrantable options
  • New construction and one-time-close timing
  • Unique construction and mixed-use, including buildings with attached commercial space

Condo and non-warrantable eligibility is project-specific. Ask early, because the answer can change which building you offer on.

How she works a file

Read the guidelines first. Then build the file.

Michele reads the underwriting guidelines and the rate matrix for your specific program, so she can tell you which documents are needed and why each one is being asked for. Requesting them up front is what keeps a file from stalling in week five.

  1. Match the Program to Your File

    Before any numbers go out, we look at what you have: income, credit, the down payment you can reach, and the property you are actually trying to buy. Then we find the program whose guidelines your file already meets, rather than the one with the best headline rate.

  2. Build the File Before Underwriting Sees It

    I read the underwriting guidelines and the matrix for your program, so I can tell you which documents are needed and why each one is being asked for. Requesting them up front is what keeps a file from stalling in week five over something we could have handled in week one.

  3. Work the Transaction Through Closing

    I will speak to the listing agent on your behalf to help your offer get accepted, and I am available after hours and on weekends because that is when offers are written. You hear from me in whatever way works for you and for everyone else in the transaction.

Run the numbers

Does the refinance actually pay for itself?

A lower rate is not a saving until it has covered what the refinance costs to do. Put in the current loan and the new one, and the calculator gives you the month it breaks even. If you are likely to move before then, the answer is no, and that is worth knowing before anyone pulls credit.

Market intelligence

Grand Traverse County and northern Michigan

Snapshot as of August 2026. Refreshed quarterly.

Median Sale Price

$420,000

571 closings, first half of 2026

Prices held while the number of sales fell about 12 percent from last year. Well-priced homes are still moving; overpriced ones now sit.

Months Of Supply

2.8 months

a balanced market is about 6

Still short on inventory, but no longer frantic. Homes average roughly 50 days on market and close near 99 percent of asking.

One County Over

$225K to $260K

Kalkaska, Wexford, Roscommon

A budget that will not stretch to Traverse City often reaches comfortably 20 to 40 minutes out. Worth knowing before you set a pre-approval number.

Seasonal Window

October to March

when the buyer pool thins

Closings drop through the winter and competing offers thin out with them. Fewer bidders, more seller flexibility, same house.

Why the experience matters

She has run the whole machine.

From 2015 to 2017, Michele was President and Owner of A.S. Financial Corporation, her own mortgage brokerage, and she calls it the highest achievement of her career. Running it meant operations, marketing, and a state audit she prepared for and passed clean. It also meant less time originating loans, which is the part she likes best, so she closed the company and went back to it. She chose the desk over the corner office.

It means the person structuring your loan has seen the business from the compliance side, the operations side, and the origination side. When she tells you why an underwriter wants something, she is not guessing.

More about Michele

In their words

How clients describe working with Michele.

“She walked us through every single step in a very easy and clear way... she worked with us patiently until we completed the whole process and never felt rushed or pressed. She listened to us and helped us to create a plan that fit our needs to obtain the house that we loved!”
Rocely S. · Home purchase, reviewed 2021

From Google reviews

“Michele Sims was exceptional since day 1! She walked us through every single step in a very easy and clear way... she worked with us patiently until we completed the whole process and never felt rushed or pressed. She listened to us and helped us to create a plan that fit our needs to obtain the house that we loved! Thanks Michele!”
Rocely S. · February 2021

See all reviews on Google

Start here

Bring the specific situation.

Not a rate question. The actual situation: the house you want, the house you have, and the timeline you are working against. That is where this is useful.

Step 1 of 2 · What’s the situation?

Two ways to start

Send the file, or talk it through first.

If you already know the shape of what you are doing, starting the application gets your documents moving and gives Michele something concrete to price. If the open question is whether the move works at all, the conversation is the better place to begin.

Opens the secure Priority Home Mortgage application in a new tab. Michele Fulcher, NMLS #139088. Equal Housing Lender.

Frequently asked

Common questions, answered straight.

If you are evaluating whether Michele is the right fit for your situation, these are the questions clients most often ask before they book a strategy session.

Who is Michele Fulcher?

Michele Fulcher is a Mortgage Loan Originator at Priority Home Mortgage, NMLS #139088. She has spent 40 years in mortgage lending and has closed thousands of client loans. She was nominated to a Who’s Who list of loan officers two years running, closing roughly $40 million a year. From 2015 to 2017 she was President and owner of A.S. Financial Corporation, her own mortgage company. She works with experienced homeowners, first-time buyers, and real-estate investors across northern Michigan.

Was Michele Fulcher previously known as Michele Sims?

Yes. Michele Fulcher originated as Michele Sims for most of her career and changed her name when she married a few years ago. Same person, same NMLS number, #139088. Client reviews and records from before the change carry the Sims name.

What areas does Michele Fulcher serve?

Northern Michigan. She is based in the Fife Lake area and works across Grand Traverse, Kalkaska, Missaukee, Wexford, and Roscommon counties, including Traverse City, Fife Lake, Kalkaska, Grayling, Cadillac, Roscommon, Houghton Lake, Kingsley. She is licensed in Michigan and Florida. She serves clients across the region rather than from a storefront office.

Why does an experienced homeowner need a loan officer rather than a bank?

Because on a second or third purchase the hard part is structure, not approval. Sequencing a purchase against a sale, deciding whether to keep the current house as a rental, pricing discount points against a break-even, and getting a condo or unusual property through review are all decisions made before underwriting, and they are where the money is.

What does Michele mean by reading the underwriting guidelines?

Each loan program publishes guidelines and a rate matrix setting out what a file must contain. She reads them for your specific program so she can tell you which documents are needed and why, and request them at the start. That is what prevents a file stalling late over something that could have been handled in the first week.

What first-time home buyer programs does Michele work with?

FHA, VA, USDA, and conventional loans through Fannie Mae and Freddie Mac, plus down-payment-assistance programs matched to what you actually qualify for. She will also run payment and cash-to-close estimates on real listings before you write an offer, and refer an insurance agent early so you have a real quote to plan around.

Can Michele help if my credit score is not high enough yet?

Often, yes. A credit simulator projects which specific action moves your score and by how much, so you spend effort on the change that actually improves your pricing. Sometimes rescoring after a correction or a paydown is enough. Sometimes waiting is the cheaper answer, and she will say so. A simulator projects rather than promises; the credit bureaus decide the actual result.

What is a DSCR loan, and does Michele do them?

Yes. A DSCR loan qualifies the property rather than the borrower: underwriting compares the rent the property brings in against the payment it has to cover. On most DSCR programs there is no employment verification and no personal income calculation, though requirements vary by program. It is useful when the write-offs that help you at tax time work against you in underwriting. Pricing and down payment differ from a primary-residence loan.

Can I close an investment property in my business name?

Yes, and there are three common reasons to. Keeping additional financed rentals off your personal debt load, holding liability inside the business for tax purposes, and staying anonymous to tenants who deal with a property manager. The entity structure itself is a question for your CPA and attorney; Michele handles the financing around it.

Does Michele work with short-term rentals in the Traverse City area?

Yes. Northern Michigan has a real short-term-rental market, and the financing follows the exit you plan at the outset. Note that rules are local: Traverse City licenses vacation rentals and restricts them by zoning district, so confirm the specific parcel before counting on that income.

How do I verify Michele Fulcher’s license?

Look up NMLS #139088 on the public NMLS Consumer Access registry. Her low number reflects how early she registered. Priority Home Mortgage is a dba of PFN Lending Group, Inc., company NMLS #103098.

When is Michele available?

After hours and on weekends, because that is when offers get written. She will also speak to a listing agent on your behalf to help your offer get accepted, and communicates by whatever method works best for you and the other parties in the transaction.

Buying your first home? Start at buyupnorth.com. Buying an investment property? That one is at buyupnorth.com/investors.